
Hunt Scanlon Ventures Sees Transaction Readiness as Key Lever Driving Human Capital M&A
November 17, 2026 – Hunt Scanlon Ventures’ 2026 Q3 M&A Report highlights a growing imbalance across the lower-middle-market acquisition landscape. Capital remains plentiful, buyer competition is intensifying, and high-quality businesses are attracting significant interest. Yet investors are becoming increasingly disciplined about which companies can deliver sustainable growth and long-term enterprise value.
The report points to approximately $1.3 trillion in global private equity buyout dry powder, much of it raised during 2022 and 2023. At the same time, research from the International Business Brokers Association and M&A Source indicates that 87 percent of completed transactions above $5 million attracted at least three offers, while approximately three-quarters of advisors characterized the $2 million to $50 million transaction market as favoring sellers.
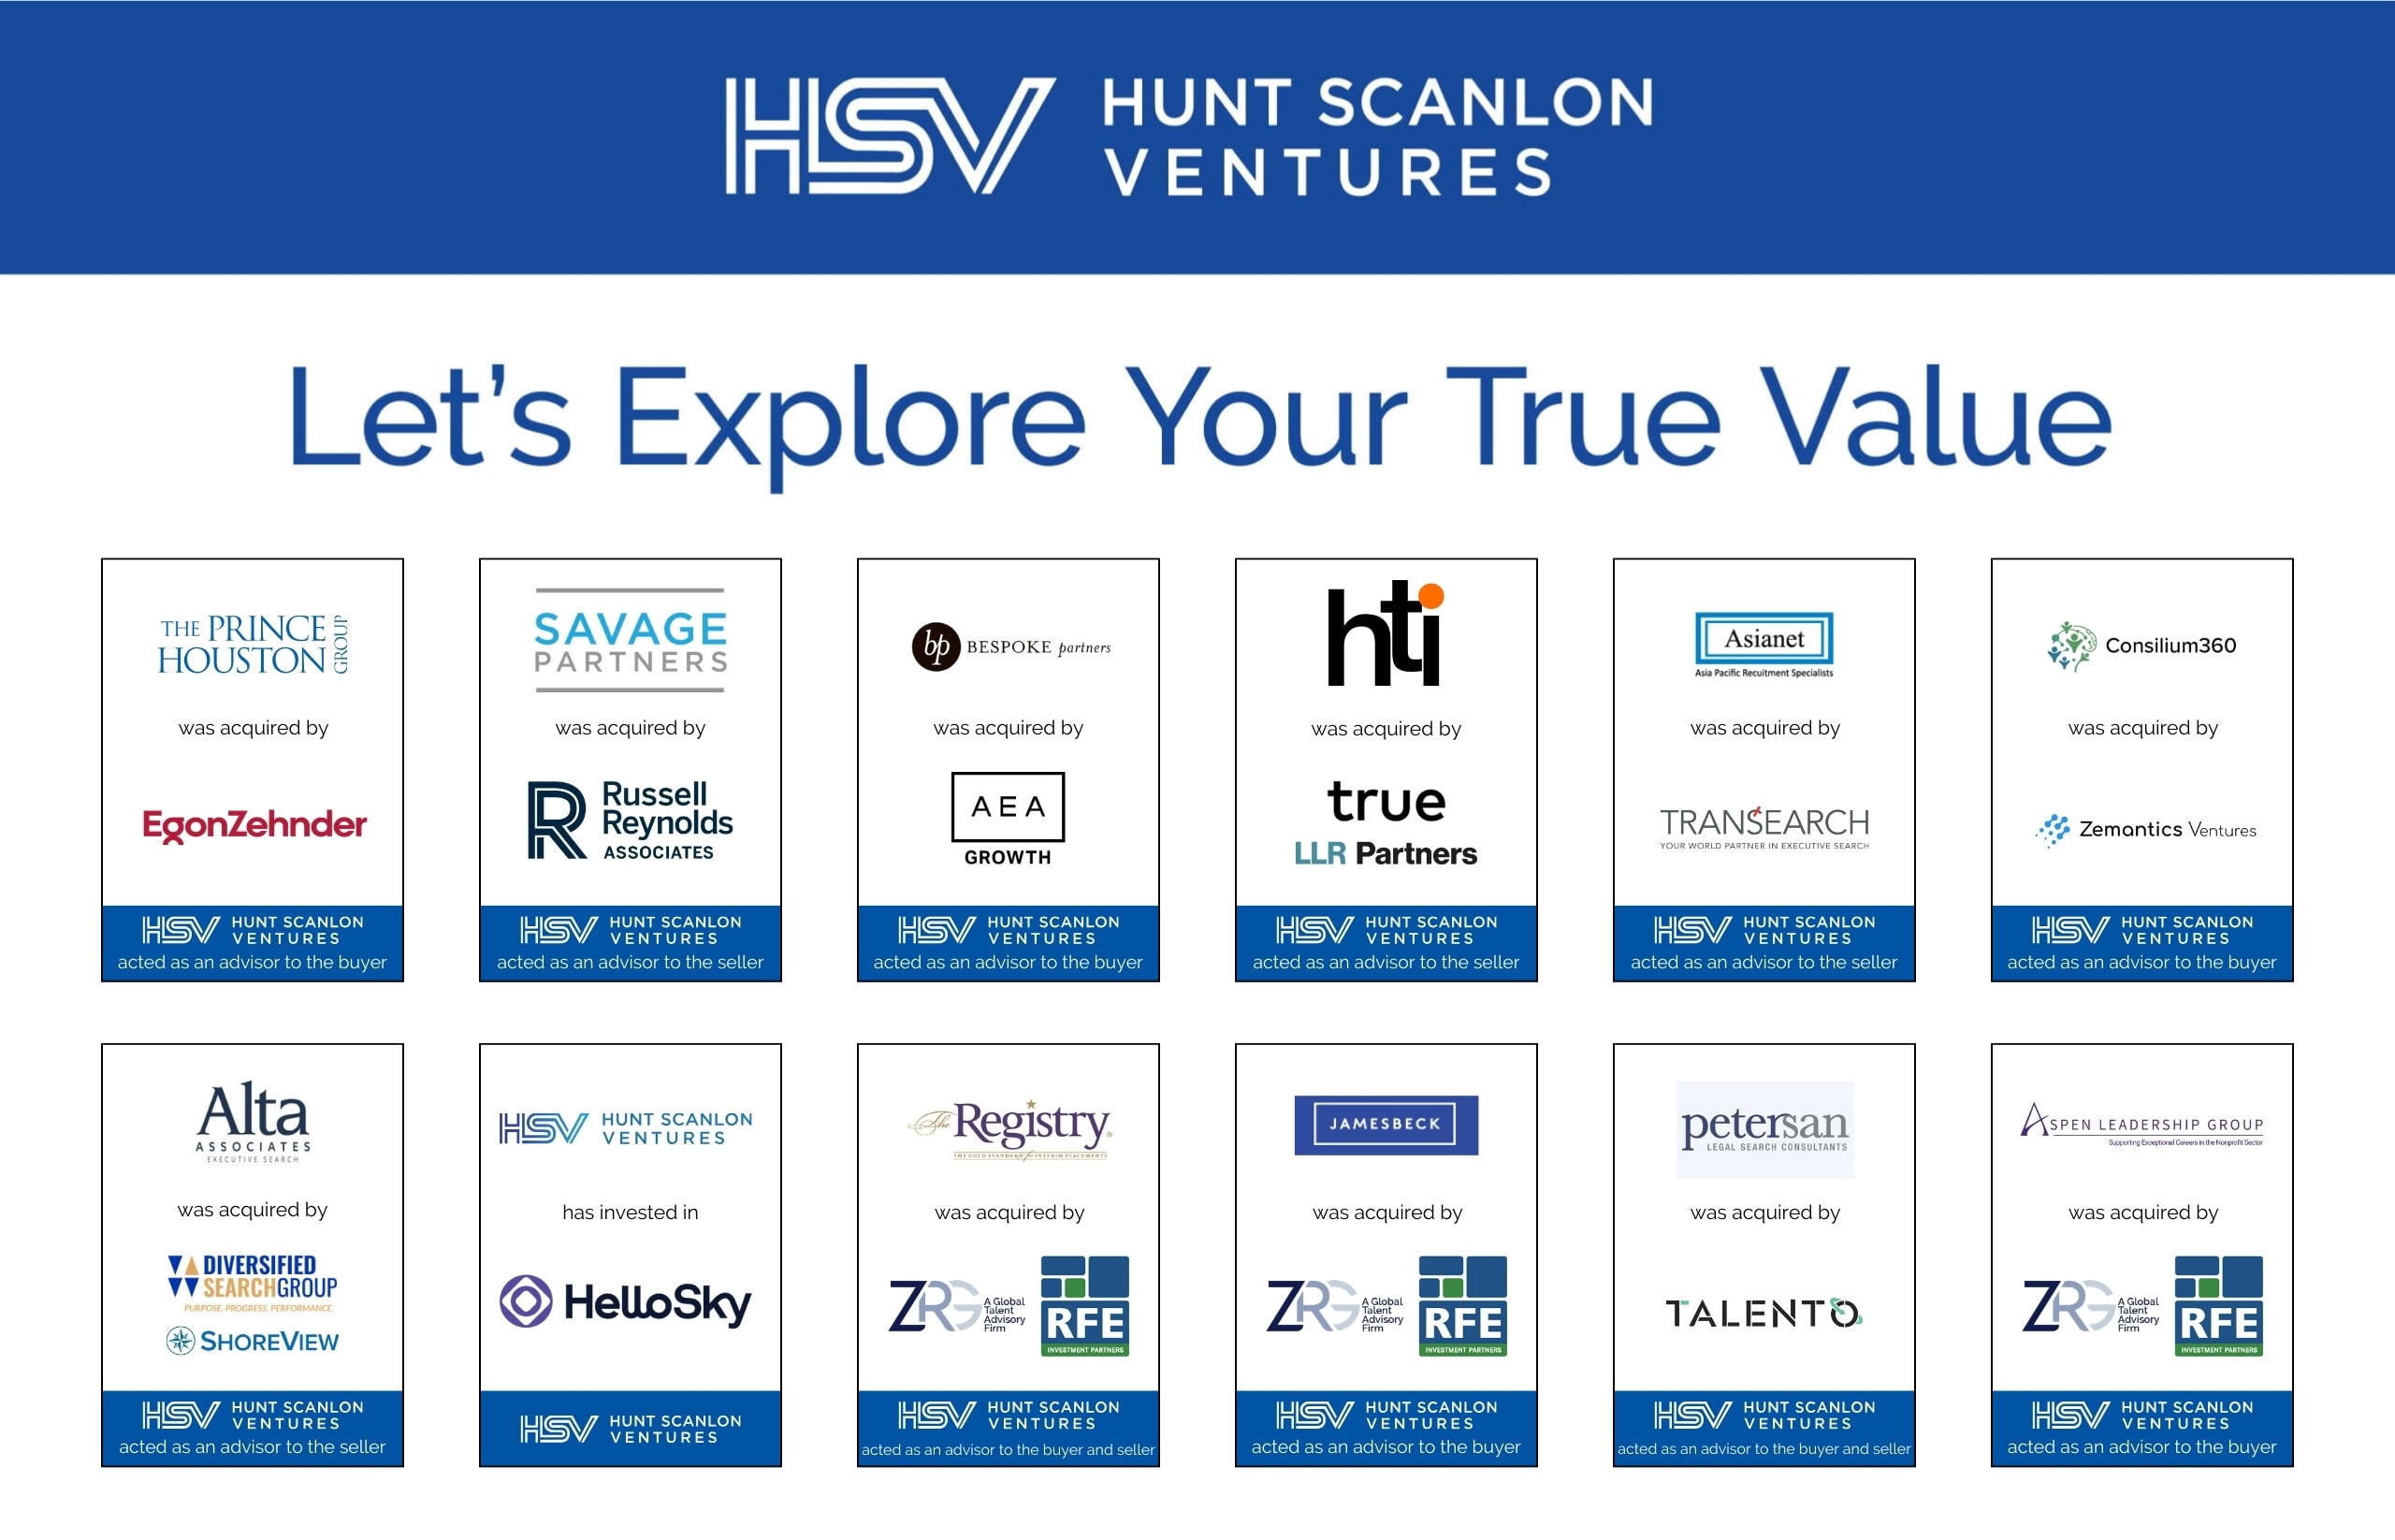 For the human capital industry, these broader market conditions carry important implications. Executive search, recruiting, staffing, and leadership advisory businesses remain highly fragmented, offering opportunities for investors seeking specialized expertise, established client relationships, and scalable platforms. But the expanding buyer universe is also creating greater differentiation between businesses that are simply profitable and those capable of sustaining performance beyond their founders.
Capital is Chasing Quality
The growing competition for attractive acquisitions is reshaping the balance between buyers and sellers. According to the Hunt Scanlon report, Axial added 2,635 new buyers to its lower-middle-market platform in 2025, a 36 percent increase from the previous year. Traditional private equity firms are increasingly competing alongside independent sponsors, family offices, strategic acquirers, and holding companies.
“The amount of capital pursuing acquisitions is substantial, but the number of businesses meeting buyer expectations remains limited,” said Scott A. Scanlon, CEO and co-founder of Hunt Scanlon Ventures. “For founders who have built strong, profitable companies with established leadership teams and durable client relationships, that imbalance can create meaningful leverage.”
However, the opportunity is not evenly distributed. Buyers are prioritizing companies with predictable earnings, diversified revenue, strong management teams, and clear opportunities for expansion. For human capital firms, where enterprise value is often concentrated in relationships and specialized expertise, demonstrating that those strengths can survive an ownership transition is becoming increasingly important.
AI Changes the Acquisition Equation
Technology is also emerging as a more significant consideration in human capital M&A. As AI moves beyond experimentation toward measurable business applications, buyers are increasingly evaluating whether acquisition targets have the infrastructure, proprietary data, and operational capabilities necessary to support future growth.
The report highlights research showing that 78 percent of recruiting firms reporting revenue growth above 25 percent used AI tools embedded within their applicant tracking systems, compared with 51 percent of firms experiencing revenue declines greater than 10 percent. While the findings cover the broader recruitment industry, they suggest a meaningful relationship between technology integration and business performance.
 U.S. M&A Accelerates as Buyers Raise the Bar
EY-Parthenon’s Merger Monthly points to continued momentum across the U.S. M&A market. Through August, deal value for transactions above $100 million reached approximately $2.2 trillion, up roughly 48 percent year-over-year, while volume increased 23 percent. Momentum remained strong from June through August, with deal value rising 23 percent and volume advancing 22 percent from the comparable period last year.
The middle market has been an important part of that expansion. Transactions between $100 million and $1 billion-plus recorded 26 percent year-over-year growth in value during the June-to-August period, supported by financing capacity and stronger buyer conviction despite geopolitical uncertainty. EY says strategic acquisitions targeting scale, market leadership, and attractive growth segments continue to underpin activity.
For executive search firms, the implications extend beyond productivity. Centralized candidate intelligence, institutional client knowledge, and repeatable operating processes can make a business less dependent on individual consultants while creating opportunities to scale.
“From an M&A perspective, the question is whether a firm’s success can be transferred and scaled,” said Drew Seaman, managing director at Hunt Scanlon Ventures. “Businesses that have centralized their institutional knowledge, established repeatable processes, and invested in modern infrastructure can present a more compelling growth story to potential buyers.”
A Broader Universe of Buyers
Another important development is the growing role of family offices and other alternative investors in private company acquisitions. Hunt Scanlon’s report highlights how family capital is moving beyond traditional fund allocations toward direct investments, creating additional potential buyers for founder-led human capital businesses.
Research from Altss estimates that the world’s 50 largest family offices collectively manage approximately $2.4 trillion in assets. The report also highlights the Hoffmann Family of Companies, whose ownership of DHR Global demonstrates how executive search and leadership advisory capabilities can complement a broader investment portfolio.
For founders, this expanding buyer universe introduces different ownership structures, investment horizons, and approaches to growth. While traditional private equity sponsors and strategic acquirers remain central to human capital M&A, family-backed investors can offer another alternative for businesses considering succession, recapitalization, or expansion.
What Buyers Want From Founders
Despite increasing competition for acquisitions, the report emphasizes that transaction readiness remains a critical differentiator. Buyers are looking beyond current financial performance to assess whether a business has the leadership, systems, and client relationships necessary to continue growing after a transaction.
For executive search and advisory firms, that means reducing dependence on founders, developing the next generation of leadership, diversifying client relationships, and strengthening financial and operational reporting. Businesses that have invested in these capabilities are generally better positioned to withstand diligence and support a compelling growth thesis.
Related: Family Offices Move Into Human Capital M&A
“From our vantage point, these conditions reinforce the importance of building enterprise value well before a transaction process begins,” said Mr. Seaman. “Financial transparency, leadership succession, diversified revenue, and operational maturity can help reduce buyer friction while positioning founders to benefit from competitive acquisition processes.”
The report also underscores the importance of aligning personal and business objectives well ahead of a potential transaction. For founders considering liquidity over the next 12 to 36 months, decisions surrounding management succession, profitability, client concentration, and technology investment can materially influence the options available when they eventually enter the market.
The Outlook for Human Capital M&A
Looking toward 2027, the forces shaping human capital M&A appear likely to remain fluid. Significant private equity capital remains available, alternative buyers are expanding their acquisition activity, and AI is creating new opportunities for businesses capable of combining specialized expertise with scalable technology.

At the same time, buyers are unlikely to abandon their focus on quality. Firms with strong leadership teams, durable client relationships, disciplined financial performance, and differentiated capabilities may continue attracting competitive interest, while businesses with concentrated revenue or limited operational infrastructure could face greater scrutiny.
For the human capital sector, the next phase of consolidation may therefore be defined less by the amount of capital available than by the ability of businesses to demonstrate sustainable enterprise value. As investors compete for a limited supply of attractive assets, founders who have built organizations capable of growing beyond their own leadership could find themselves in an increasingly advantageous position.
The broader message from Hunt Scanlon Ventures’ latest report is that opportunity remains substantial, but preparation and differentiation are becoming more important. For executive search, recruiting, and leadership advisory firms considering their next chapter and a founder exit, the work required to achieve a successful transaction increasingly begins long before a buyer enters the picture.
Reprinted with permission from ExitUp!
Contributed by Scott A. Scanlon, Co-CEO, Evan Berta, associate – Hunt Scanlon Ventures